Buying Property in Portugal From the UK? Get Your NIF and Bank Account Before You Find the House
Most people find the house first and deal with the paperwork second.
Then someone asks for your NIF.
That’s usually when buyers find out about the two things they should have sorted months ago: a Portuguese tax number (NIF) and a Portuguese bank account.
Without the first, you can’t sign for the property.
Without the second, every payment for the house goes by international transfer or through your lawyer. And once you own it, your first water bill arrives with a Multibanco reference your UK bank can’t pay.
Both take a few weeks. Neither needs a trip to Portugal.
Do you need a NIF to buy property in Portugal?
Yes. You need a Portuguese tax number (NIF) before you can sign the promissory contract (CPCV) for a property in Portugal. You also need it to pay the property transfer tax (IMT) and stamp duty, to sign the deed, and later to set up water and electricity and pay the yearly property tax (IMI).
Once an offer is accepted, the CPCV can come round within weeks. That’s not the moment to start applying.
You can get a Portuguese NIF from the UK without travelling. You send a passport scan and a recent proof of your UK address, and sign a power of attorney online. A partner lawyer in Portugal registers the number for you.
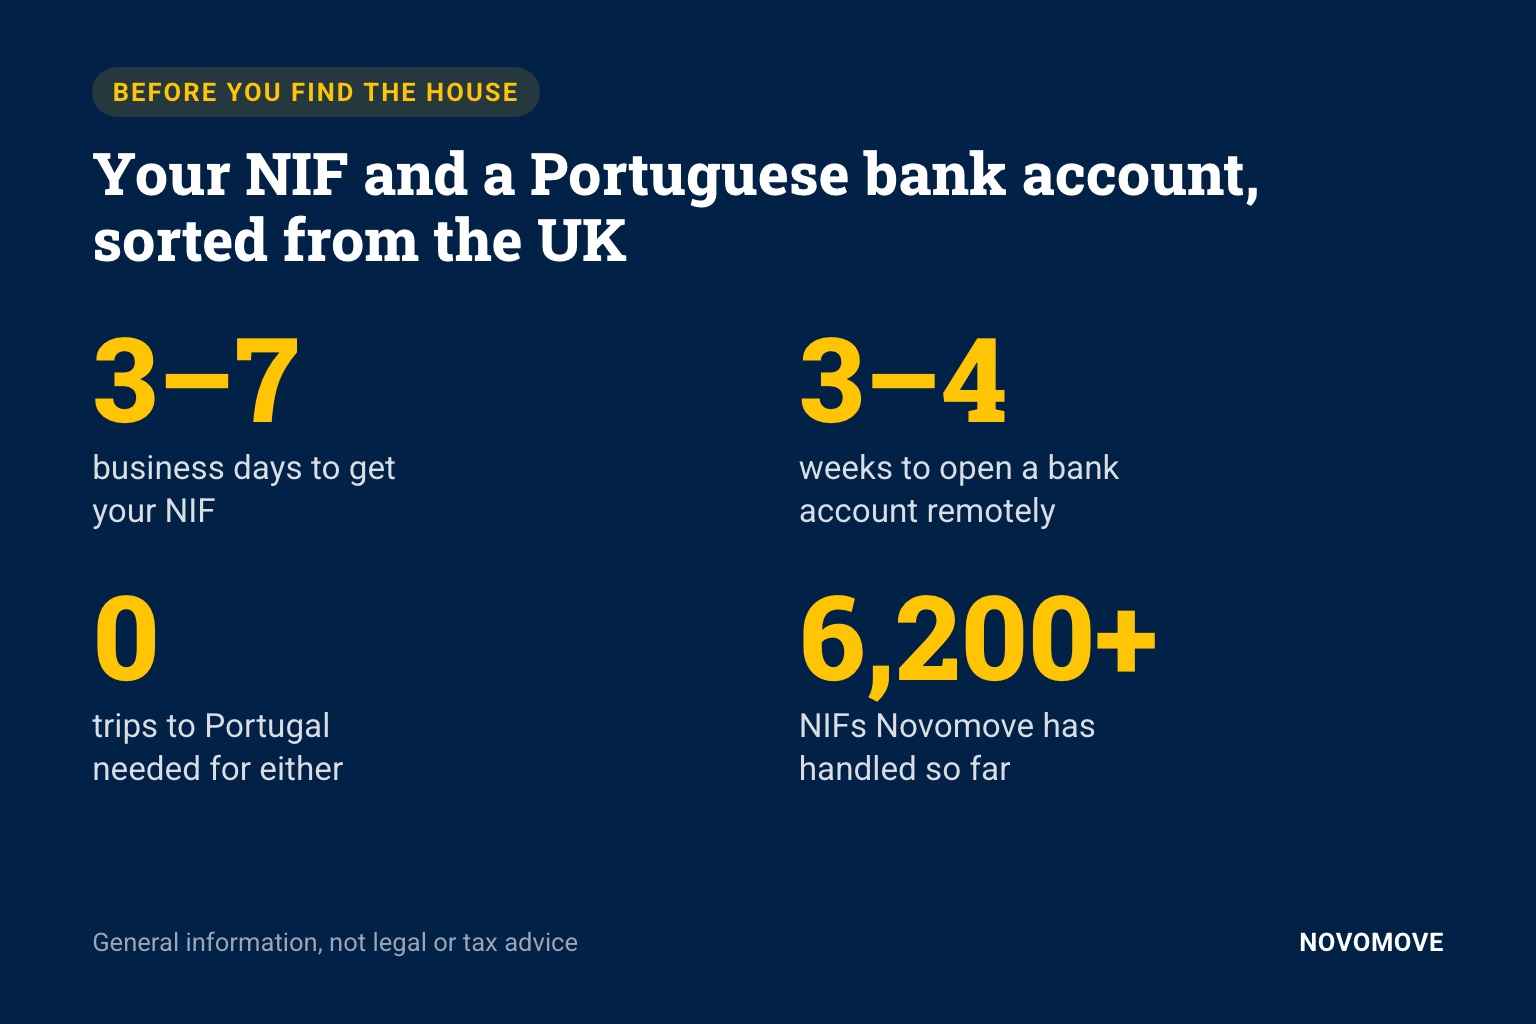
It usually takes 3 to 7 business days.
Buying as a couple? You each need your own.
Does a NIF make you a tax resident in Portugal?
No. Getting a NIF doesn’t make you a Portuguese tax resident. A NIF issued while you live in the UK is registered to your UK address, so the tax office treats you as a non-resident. That changes when you move to Portugal and update the address on your NIF to a Portuguese one.
If you have no Portuguese income, a non-resident NIF doesn’t come with a yearly tax return. Once you own a house, you pay the IMI bill when it arrives. (Renting it out is a different story. That one’s for an accountant.)
Do you need a fiscal representative in Portugal?
Usually, yes. If you live outside the EU, and since Brexit that includes the UK, the Portuguese tax authority needs a way to reach you about your tax matters. Most UK owners use a fiscal representative: a person or firm in Portugal who receives letters from the tax office (Finanças) and forwards them to you. The alternative is switching on electronic notifications on the tax portal.
However even with electronic notifications on, some notices still only come by post. Audits, fines, legal summonses.
Portuguese tax letters are a bit like cats. They turn up when you least expect them, and ignoring them never ends well.
So if you own property in Portugal and still live in the UK, keep a representative for as long as you’re a non-resident.
Can you buy property in Portugal from a UK bank account?
Yes, but every payment needs a workaround. You can pay the deposit and the full amount from a UK account by international transfer. The taxes due before the deed (IMT and stamp duty) are paid with a Portuguese payment reference that UK banks can’t handle, so most buyers send that money to their lawyer to pay. And a Portuguese mortgage needs a Portuguese account.
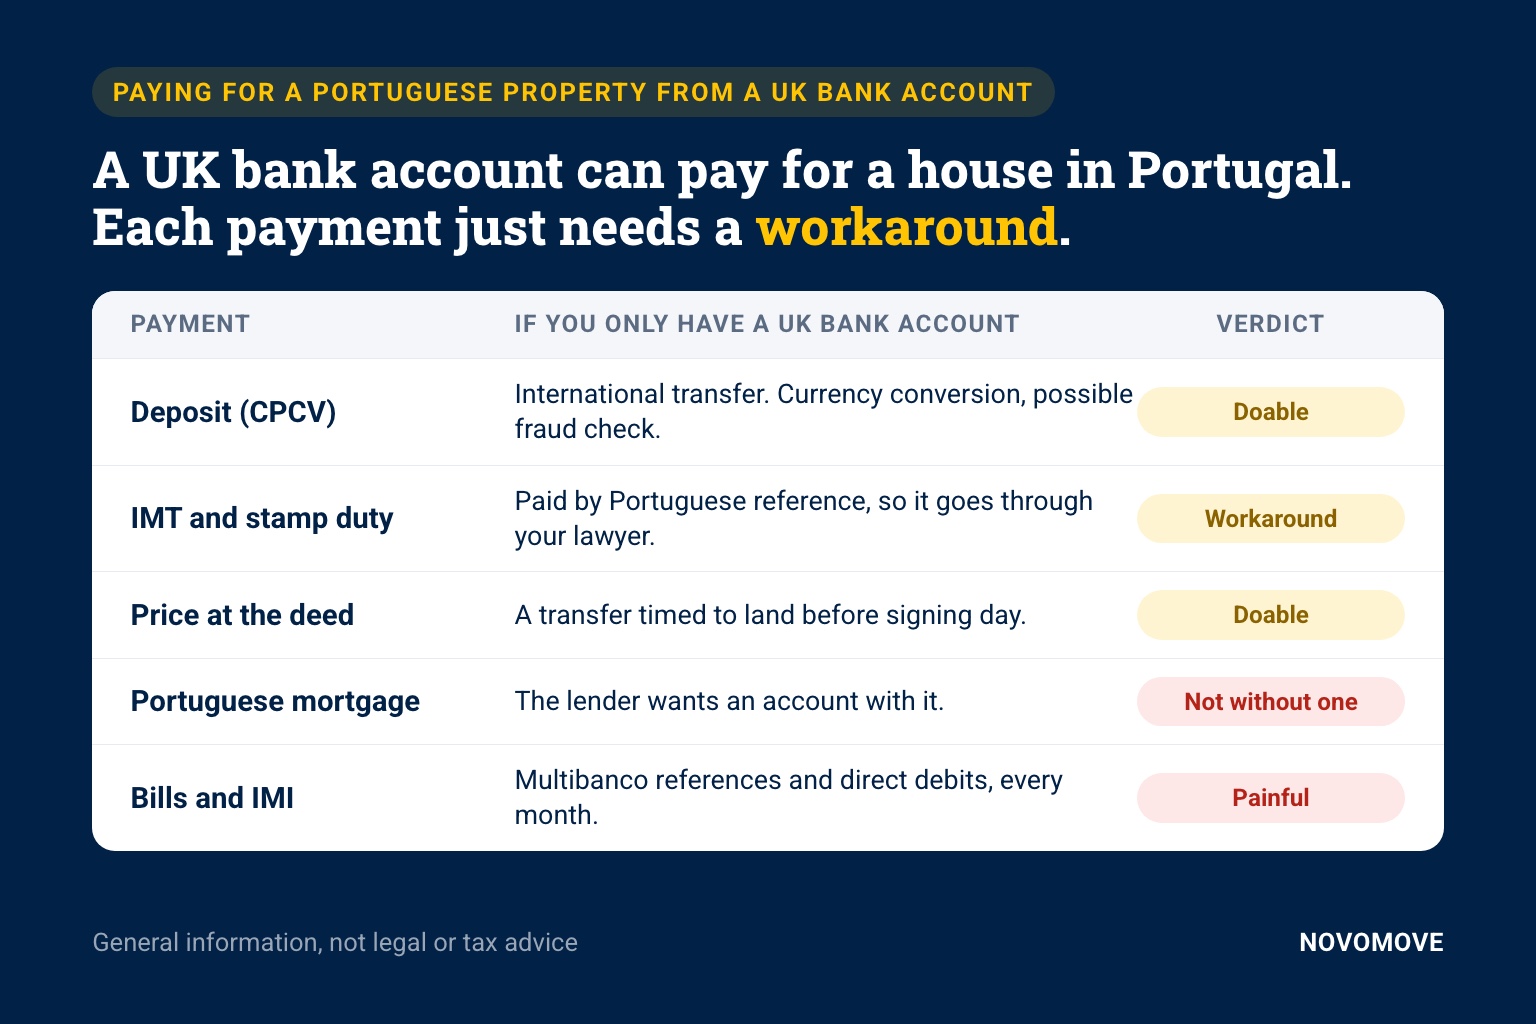
Here’s how it plays out.
The deposit. You sign the promissory contract and send the deposit abroad. It’s a big overseas payment, so expect a currency conversion, a day or two in transit, and possibly a fraud check from your UK bank. Most buyers use a currency specialist rather than their high-street bank. On a house-sized sum, the difference in rate adds up.
The taxes. IMT and stamp duty are paid before the deed, with a reference generated under your NIF. Portuguese banking apps have a button for paying the state. UK banks don’t. So the money goes to your lawyer’s client account and your lawyer pays it. One more step, on a deadline, because the deed can’t go ahead until the tax shows as paid.
The price. On deed day the balance is paid by bank transfer, or by a banker’s draft from a Portuguese bank, which is the traditional way. From a UK account, you’re timing a transfer to land before signing day.
It also has to be your money. The deed records how the price was paid, and anti-money-laundering rules mean the funds must trace back to you. A relative paying from their own account will raise questions.
The mortgage. If you borrow from a Portuguese bank, it will want you to hold an account with it. No way round that one.
Then you get the keys. Water, electricity and IMI arrive with Multibanco references or need a direct debit. That’s where a UK-only setup stops being awkward and starts being annoying, every single month.
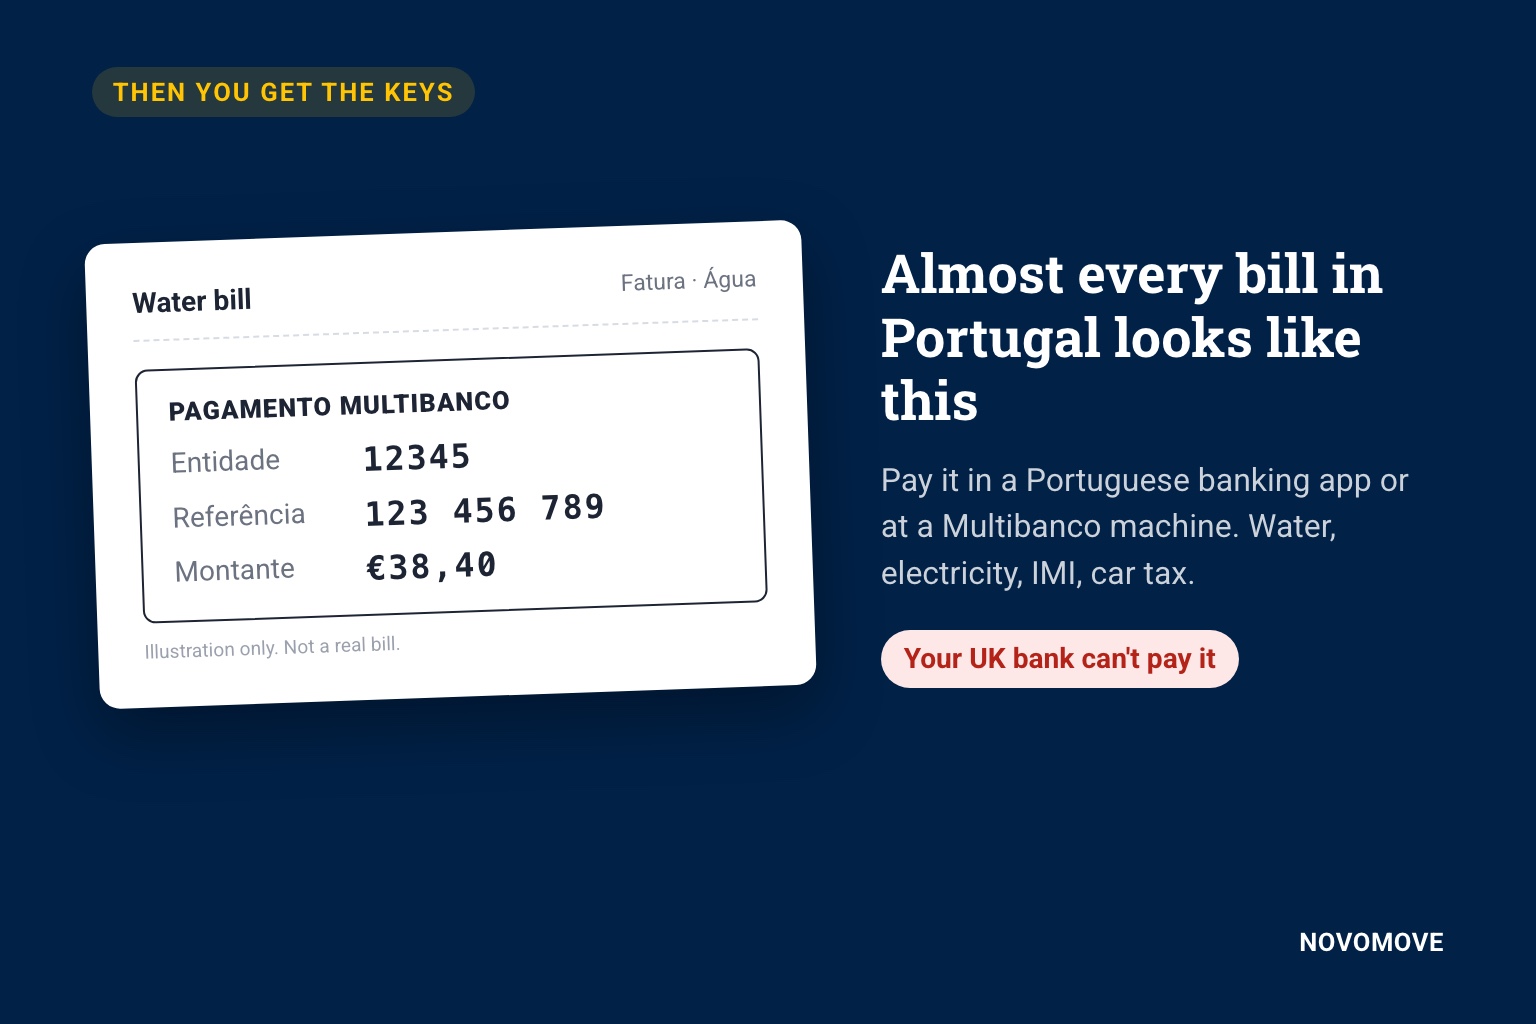
One owner on an expat forum, back home with overdue car tax, was told to find someone in Portugal to pay it for them.
Can you open a Portuguese bank account online as a non-resident?
Usually not. Most Portuguese banks offer online account opening only to people who hold a Portuguese Citizen Card. Non-residents are normally asked to apply in person instead, either at a branch in Portugal or at one of the bank’s offices abroad, with certified copies of their documents and printed forms.
You’d think it would be easier. It’s 2026, after all.
A few Portuguese banks have offices in the UK, but you still have to go there yourself. And documents certified outside Portugal usually need a Hague Apostille or a stamp from a Portuguese consulate.
So we do it differently. Our partner bank opens the account remotely, and a partner law firm in Portugal certifies your signature.
No branch visit. No apostille. No day off work queuing at a consulate.
Can UK citizens open a Portuguese bank account without a visa?
Yes, with the right bank. Our partner bank treats UK applicants the same as EU applicants, so British buyers can open a Portuguese account remotely without a visa or a visa appointment.
At the same bank, applicants from outside the EU and UK, such as the US or Canada, have to show they’re applying for a Portuguese visa first.
That means you can open the account while you still live in the UK. Holiday home or a move years away, it doesn’t matter.
What you’ll usually need:
- your passport
- a utility bill or bank statement showing your UK address (a tenancy agreement won’t do)
- proof of income or savings
- your NIF
- your UK tax number
- a short letter saying why you’re opening the account (we send you a template)
English documents are fine. It takes 3 to 4 weeks. The bank asks for a small opening deposit, which stays in your account, and charges its own monthly fee.
Can you open a bank account in person on a viewing trip?
Sometimes. Some branches in Portugal will open an account for a non-resident with a NIF, but many won’t, and there’s no standard rule across banks or branches. Even when a branch says yes, the account is rarely opened the same day, because most banks send the file to their compliance team first. That can take from a few days to a few weeks, so plan for at least two visits.
Bring your passport, your NIF and some patience. And plan for a no.
One visit to apply, one to finish. There’s a pastelaria near most branches, which helps.
If you try it, go in the first days of your trip, not the last. If your viewings run over a few weeks, the second visit can fit in before you fly home.
If it doesn’t work out, we can still open the account remotely.
How long do a NIF and a bank account take?
Allow about 5 to 6 weeks for both. A NIF takes around 3 to 7 business days, and a remote bank account takes another 3 to 4 weeks once you have the NIF. The best time to start is when you book your first viewing trip, not when you’ve found the house.
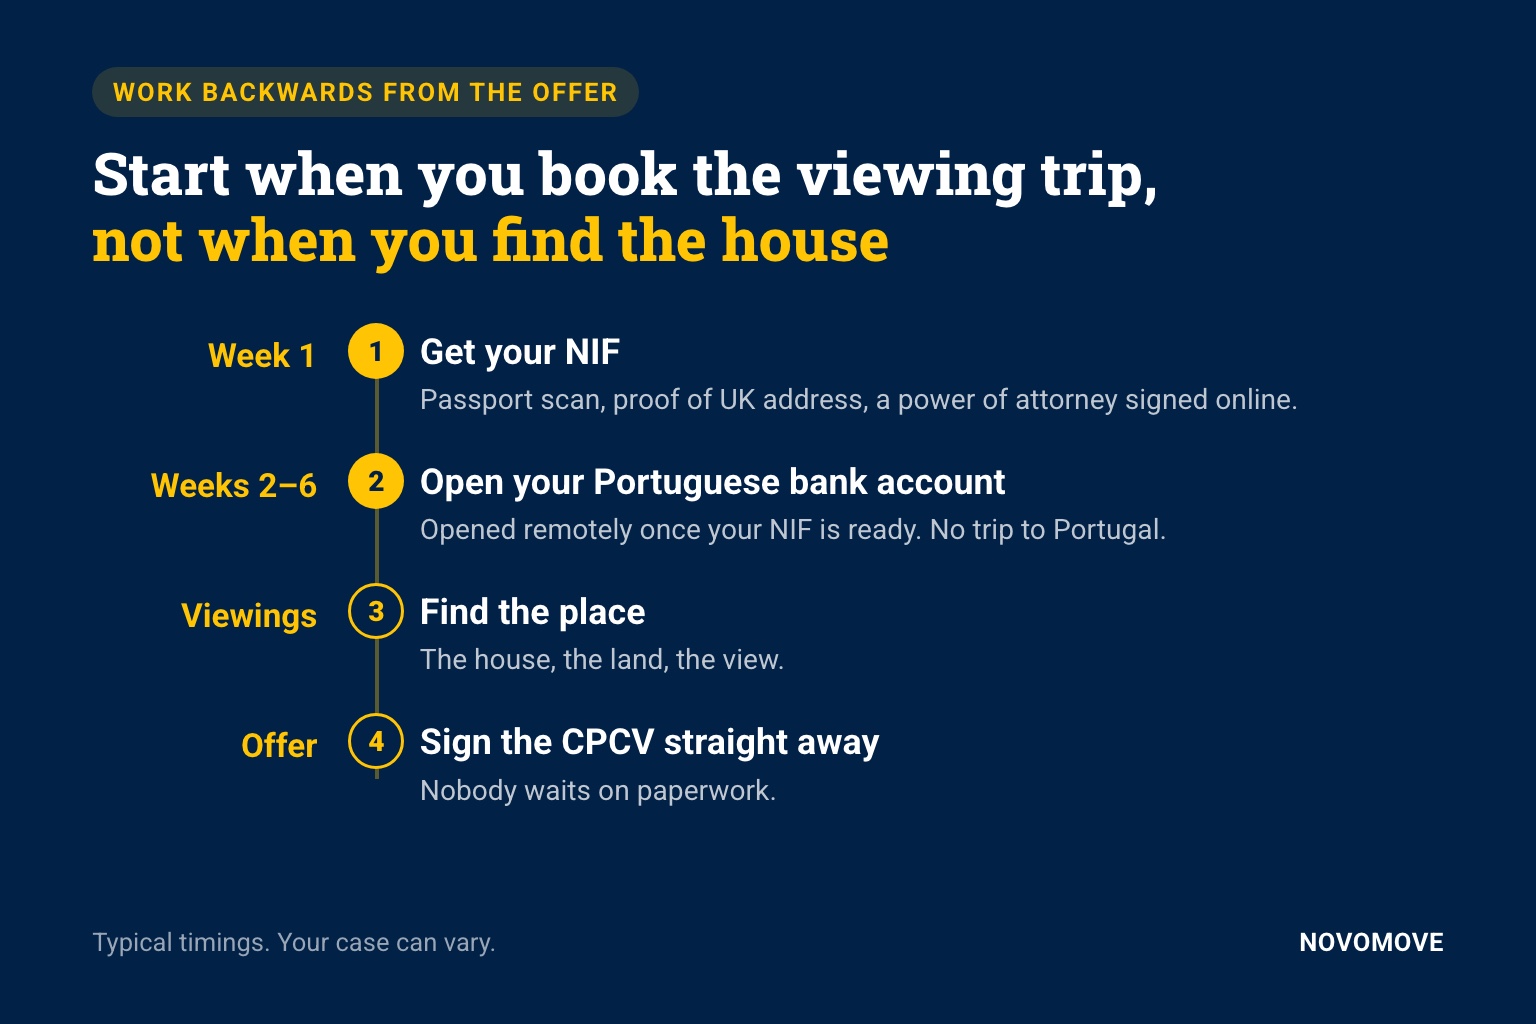
Your NIF is yours for life. So when the right place turns up, you make the offer and sign. Nobody wants to wait on paperwork at this stage.
Then you can get back to the good part. Like deciding which room becomes the guest room, and how many friends are suddenly keen to visit.
Getting both
It’s cheaper to order them together. There’s a Solo bundle (a NIF and a bank account) and a Couple bundle (two NIFs and a joint account).
Pure Portugal readers also get a code for a NIF or a bank account ordered on its own. You’ll find the code, and a link to our current prices, on our page for Pure Portugal readers: novomove.com/pureportugal
Not sure where to start? Book a free 15-minute call and tell us about the house you’re dreaming of. Or find us on the Pure Portugal Journey Hub.
See you in Portugal,
Philip
This guide is general information, not legal or tax advice. Bank requirements change, so check your own situation before you apply.